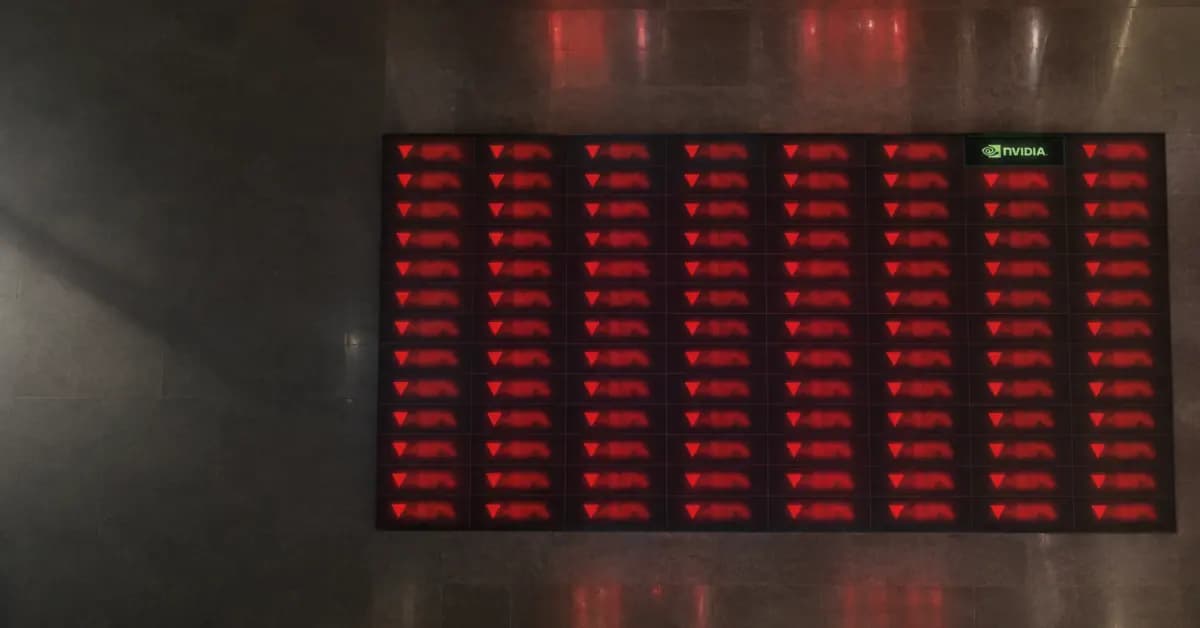
Strong corporate reports failed to calm global equity markets as selling pressure spread across US, European, and Asian exchanges. Daniela Hathorn, senior market analyst at Capital.com, an online trading platform, stated in a market note that investors are conducting a broad reassessment of risk rather than a narrow technology correction. Hathorn noted that market participants remain skeptical about whether corporate profits can justify elevated valuations in an environment marked by persistent inflation and restrictive monetary policy.
Disconnect Between AI Results and Broad Indices
The standout development of the week centered on the contrasting performance of artificial intelligence leaders and the broader market. According to the note, artificial intelligence computing infrastructure supplier NVIDIA posted quarterly revenue of $115.8 billion with forward guidance of $130 billion. However, these figures did not restore wider sector confidence, with Hathorn observing that investors remain worried about the sustainability of capital expenditure and uncertainty surrounding the leadership transition after Jensen Huang departed.
“What initially looked like a correction concentrated in technology stocks has increasingly become a broader reassessment of risk, as investors question whether corporate earnings can justify elevated valuations in an environment of persistent inflation and restrictive monetary policy.”
Daniela Hathorn, Senior Market Analyst at Capital.com
Public market appetite was also tested by Anthropic on the Nasdaq, where shares were priced at $83 and reached an opening price of $111.50 before ending the first trading day near $97. Hathorn wrote that while this represented a 17% gain over the initial offer price, the Nasdaq composite still dropped more than 2% during that session.
Selling Extends Across International Equities
Selling momentum was not restricted to US tech indices alone. The note highlighted that the S&P 500 recorded six consecutive daily declines, European markets lost their earlier resilience, and Asian technology shares experienced steep declines as traders trimmed exposure across the hardware supply chain.
Pressure on Global Equity Markets
Broader headwinds for global equity markets deepened as central bank signals limited relief options for risk assets. According to the analysis, minutes from the October Federal Reserve meeting reinforced expectations of a 25-basis-point interest rate increase in December, with borrowing costs projected to remain elevated into 2027.
Hathorn noted that the US dollar held near its highest level in 19 months, while commodity markets struggled as Brent crude faced supply adjustments through the Strait of Hormuz and gold dropped toward $3,700. In the note, Hathorn explained that simultaneous weakness in equities and precious metals indicates investors are focusing heavily on liquidity and capital preservation.
Inflation Data and Economic Outlook
Looking toward upcoming trading sessions, the US economic calendar features the October Personal Consumption Expenditures price report, which represents the Federal Reserve preferred inflation benchmark. Hathorn stated that another elevated inflation print could prolong the market correction by cementing higher rate expectations. Conversely, stabilizing rate expectations could offer relief to global equity markets if price pressures soften, according to the economy assessment in the note.